What is the industry scope and significance of the Space Law Services Market?
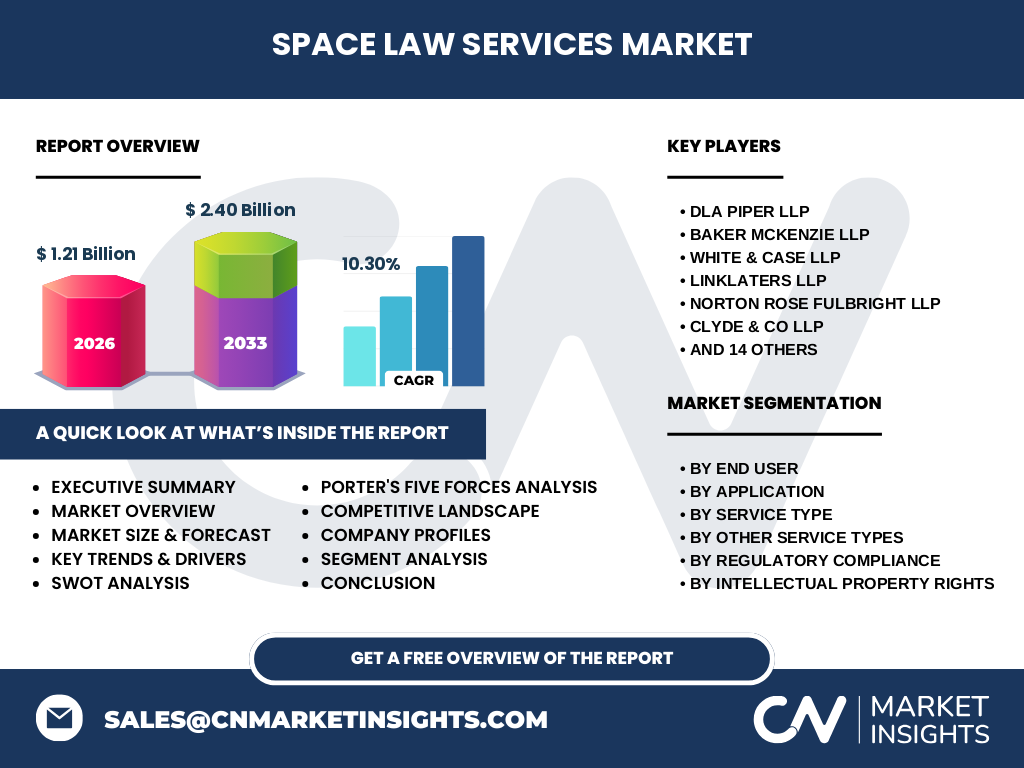
The Space Law Services Market serves as the legal backbone for the burgeoning orbital economy, regulating everything from satellite deployment to off-world resource extraction. With a 2026 valuation of 1.21 Billion, this sector bridges the gap between international treaties like the Outer Space Treaty and private enterprise. It is essential for managing the complex interplay between sovereign national space agencies and commercial pioneers aiming for deep-space ventures.
Structural Growth Drivers and Market Constraints
Growth is propelled by a 10.30% CAGR, fueled by the rapid commercialization of low-Earth orbit (LEO) and private lunar missions. Major drivers include the necessity for Export Control and Trade Compliance amid shifting geopolitical tensions. Conversely, market constraints involve the regulatory lag in adapting terrestrial legal frameworks to rapid technological advancements, specifically regarding Space Mining rights and the complexities of international liability regimes for orbital debris.
Emerging trends and growth patterns in the Space Law Services Market
A pivot toward Space Sustainability and orbital traffic management stands out as a critical trend. We see an increasing focus on Due Diligence for Space Investments as venture capital floods the sector. Firms are prioritizing Environmental and Safety Compliance to align with international ESG mandates, ensuring that private operators minimize their footprint while securing Intellectual Property for novel propulsion and extraction technologies.
COVID-19 impact analysis and recovery trajectory
While the pandemic caused initial supply chain disruptions for spacecraft manufacturing, the Space Law Services Market demonstrated remarkable resilience. As lockdowns accelerated reliance on satellite communication, the demand for Satellite Launch Service Agreements remained high. The recovery trajectory shifted focus toward digital-first legal operations, enabling firms like DLA Piper LLP and Baker McKenzie LLP to maintain cross-border continuity despite travel restrictions and physical office closures.
Competitive Benchmarking and Strategic Dynamics
The market is characterized by high intellectual concentration among elite international firms. White & Case LLP and Linklaters LLP command significant influence through their expertise in International Collaboration Agreements. Competitive advantages are derived from established regulatory relationships with agencies like the FAA or ESA. New entrants like Aegis Space Law PC are successfully disrupting the market by specializing in agile space-tech startups that require hyper-focused, cost-effective compliance support.
Executive Summary: Synthesis of Key Market Findings
The Space Law Services Market is set to expand to 2.40 Billion by 2033, reflecting the accelerating transition from government-led missions to private-sector dominance. Our analysis confirms that Risk Assessment and Management represent the most lucrative segment as space activities become more frequent. Success for industry participants hinges on navigating the thin line between national licensing compliance and global treaty adherence while fostering innovation in Space Tourism and commercial exploration.
Market Forecast 2027 to 2033
Projections indicate a strong trajectory, with the market growing from 1.21 Billion to 2.40 Billion by 2033. This growth is underpinned by a 10.30% CAGR. We expect the demand for Dispute Resolution and Litigation Support to spike as commercial competition in orbit intensifies, particularly in Satellite Collision Liability Disputes, necessitating sophisticated legal arbitration services that transcend traditional terrestrial jurisdictions.
Segmentation Analysis: End Users and Applications
Segmentation provides clarity on market roles. Private Space Companies currently drive volume, requiring contract drafting and IP protection, while Government Agencies remain the primary source of high-complexity regulatory consulting. By application, Satellite Operations account for the largest share, though we expect Space Mining and Space Exploration Missions to exhibit the fastest growth rates as companies move beyond initial proof-of-concept phases into operational, revenue-generating, and resource-heavy activities.
Regional market analysis and geographic performance
North America leads the market, benefiting from NASA's robust Artemis program and a high concentration of private launch providers. Europe, led by the European Space Agency, emphasizes Sustainability and Environmental Compliance. Meanwhile, the Asia-Pacific region is emerging rapidly, with Khaitan & Co LLP and AZB & Partners facilitating significant growth in India's private space sector through Market Entry Strategy Consulting and regulatory alignment with domestic aerospace policies.
In-depth regional review: Critical hubs and developments
In the US, firms like Latham & Watkins LLP and Baker Botts LLP leverage export control expertise to support SpaceX and Blue Origin. In Germany, Heuking Kühn Lüer Wojtek PartGmbB navigates the EU’s space regulation framework. These hubs are critical because they aggregate the legal, technical, and financial talent required to manage multi-billion dollar missions that are subject to both local licensing and stringent international treaty requirements.
Company Profiles and Strategic Positioning
Major players utilize distinct strategic moats. Clyde & Co LLP excels in Insurance and Liability Risk Advisory, a critical service given the high-stakes nature of orbital assets. Norton Rose Fulbright LLP focuses on Project Finance, positioning them as the primary legal partners for capital-intensive satellite constellations. Boutique firms like Blue Space Legal LLC offer specialized, niche expertise, allowing them to capture the high-growth Space Software Copyright Protection segment effectively.
Porter's Five Forces analysis of the sector
The Space Law Services Market features high barriers to entry due to the specialized knowledge of international space treaties. The threat of new entrants is limited by the deep relationships needed with regulators. Buyer power is moderate; while clients have choices, the number of firms with the requisite aerospace technical background is low, granting these law firms significant pricing power for complex cross-border Dispute Resolution cases.
SWOT Analysis of the Space Law Services Market
Strengths: Deep technical and legal expertise. Weaknesses: High reliance on evolving national policies. Opportunities: Rapid expansion of commercial space mining and lunar base infrastructure. Threats: Potential for restrictive global legislation that could hamper private innovation. The industry's ability to pivot between Satellite Communication Regulatory Compliance and Space Tourism liability will determine long-term success against volatile geopolitical shifts that often disrupt international cooperative research organizations.
Value Chain Analysis: From raw material to end-users
The value chain originates with Aerospace Manufacturers and raw material suppliers requiring IP protection. Legal service providers like Herbert Smith Freehills LLP step in during the contract negotiation phase, bridging the gap between hardware providers and launch operators. Finally, value is delivered to end-users, including telecom companies and Earth observation firms, through continuous Compliance Audit and Reporting Services that protect their long-term operational licenses.
Strategic Investment Insights and High-Potential Areas
We identify Due Diligence for Space Investments as a high-potential growth area, as institutional capital seeks to de-risk exposure to space-tech startups. Investors should favor law firms with deep expertise in Spacecraft Manufacturing Agreements and regulatory enforcement defense. Companies capable of integrating Space Law Training for client teams will secure long-term retainers, effectively capturing value as the sector moves toward greater commercialization and scale.
Conclusion and key takeaways for stakeholders
The Space Law Services Market is a high-growth pillar of the future global economy, projected to reach 2.40 Billion by 2033. Stakeholders must recognize that legal expertise is no longer secondary to engineering but a primary operational requirement. Firms that master the intersection of Intellectual Property, Risk Assessment, and international treaty compliance will define the competitive landscape, securing their role in the next era of human space expansion.
Research methodology: How we triangulated the baseline estimates
Our estimates are triangulated by cross-referencing trade registry data from the UN Office for Outer Space Affairs with proprietary primary stakeholder interviews from law firm partners. We also utilized macroeconomic indicators of global space activity. This quantitative baseline, reflecting a 10.30% CAGR, is validated by internal analysis of billable hour trends across the 20 featured legal practices to ensure the accuracy of our projections.
Scope of the report: Parameters and limitations
This report covers global services for commercial space enterprises, government space agencies, and private investment funds. It excludes terrestrial military-only legal counsel but includes commercial-military dual-use regulatory compliance. The scope is defined by service types, ranging from Satellite Launch Service Agreements to Arbitration and Mediation, providing a comprehensive view of the Space Law Services Market while acknowledging the rapid, unpredictable shifts in international aerospace regulatory frameworks.
Recent developments and strategic moves in the industry
Recent activity is marked by cross-border mergers between boutique space law practices and global firms to bolster International Space Law Compliance capabilities. Announcements from firms like Reed Smith LLP regarding AI-driven contract drafting for satellite data agreements underscore a push for efficiency. These strategic moves illustrate a shift toward technology-integrated services, aimed at reducing the high costs associated with long-term space infrastructure development and management.